 United States
 Macau, China
 France
 Philippines
 Singapore
 Netherlands
 United Kingdom
 Canada
 Argentina
 Germany
 Estonia
 Peru
 Russia
 Australia
 South Africa
 Nigeria
 Malaysia
 Singapore
 India
 Finland
 China
 Ukraine
 Hong Kong
 Cyprus
 Turkey
 Greece
 Sweden
 South Korea
 Mexico
 Poland
 Ireland lottery results
 New Zealand lottery results
 Puerto Rico lottery results
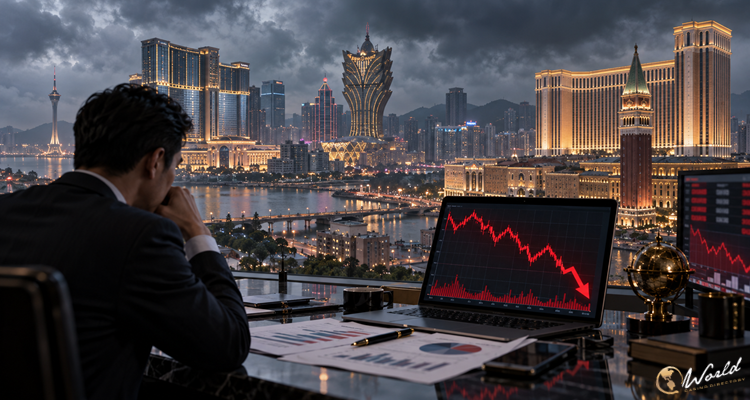
Texas Capital Securities has downgraded Melco Resorts & Entertainment from Buy to Hold, reducing its price target from $8 to $5.50 as uncertainty over Macau’s gaming market clouds the casino operator’s earnings outlook.
The assessment, issued by analyst David Bain on Friday and cited by Investing.com, reflects a widening gap between his third- and fourth-quarter 2026 earnings before interest, taxes, depreciation and amortization (EBITDA) forecasts and broader market expectations. The firm also cited limited visibility over Macau gross gaming revenue (GGR), continued promotional spending by casino operators and economic pressures in mainland China.
Melco shares fell 2.31% in midday trading following the downgrade, according to the second source, with trading volume exceeding twice the daily average. The decline extended a longer downturn in which the stock had lost 48.5% of its value over the preceding year.
Despite lowering its rating, Texas Capital acknowledged that Melco trades below its historical enterprise value-to-EBITDA ratio and has a free cash flow yield above 20%. Bain said the firm could reconsider its position if market earnings estimates become more realistic and Macau’s gaming revenue stabilizes.
The revised $5.50 target implies potential upside of more than 30% from the share price cited in the report. However, Texas Capital warned that volatility across Melco shares and the wider casino sector remains elevated.
Macau Revenue Outlook Remains Uncertain
The downgrade reflects concerns about the operating environment in Macau, where casino operators face inconsistent gaming demand despite an increase in visitors from mainland China.
Bain said September’s gross gaming revenue, when extrapolated to a daily rate, represented the weakest month for Macau concessionaires since January 2025. Checks conducted in mid-October also indicated that the market had yet to show a meaningful improvement.
The revenue outlook faces pressure from several factors in China’s economy. Texas Capital identified prolonged deflationary conditions, weakness in the property market and lower employment as potential influences on gambling expenditure.
A new Chinese tax on offshore trust assets has introduced another source of uncertainty. The 20% tax, introduced in July 2026, applies to assets held in offshore trusts and reportedly prompted some restructuring and capital liquidation. The rules also apply retroactively to the early 2020s, according to Bain’s assessment.
The analyst believes these changes could affect the amount of money available to some gamblers, complicating forecasts for Macau’s gaming revenue.
State Council Order No. 841 presents an additional concern for Texas Capital. The firm said the measure may lead to greater immigration scrutiny of intermediaries, adding another potential constraint to the market’s revenue outlook.
The combination of economic pressures, regulatory developments and inconsistent gaming activity has made it harder for analysts to estimate Macau’s near-term performance. The uncertainty is particularly relevant to Melco because its business targets premium-mass customers and, to a lesser extent, VIP gamblers.
Promotional Spending Pressures Casino Operators
Competition for higher-spending customers has intensified as Macau’s traditional junket system has largely disappeared. Casino operators have responded by increasing promotional offers and other spending intended to attract and retain players.
That activity can support customer demand, but it also raises the cost of competing for gaming revenue. Texas Capital expects the current level of promotional expenditure to remain a concern for operators seeking stronger earnings.
The analyst’s comments suggest that promotional spending may remain high even if visitation improves. An increase in visitors does not necessarily translate into stronger gaming revenue, particularly when a larger proportion of arrivals choose not to gamble.
For Melco, elevated spending could limit the benefit of any recovery in customer activity. The company competes for premium-mass and VIP players, whose spending patterns can materially influence casino performance.
Texas Capital’s lower price target reflects a reduced valuation multiple applied to Macau EBITDA. The firm’s position could improve if consensus earnings estimates adjust to reflect current trading conditions and Macau GGR begins to stabilize.
Previous Results Add to Earnings Concerns
Melco’s latest reported quarterly results provide additional context for the reassessment. In the second quarter of 2026, the company reported earnings of $0.02 per share, below analysts’ expectations of $0.09. Revenue reached $1.25 billion, compared with forecasts of $1.28 billion.
The company attributed the weaker performance to lower visitation, a softer hold and an unfavorable VIP win rate. Adjusted property EBITDA came to approximately $304 million, increasing to $312 million after accounting for VIP hold variance.
At City of Dreams Macau, an unfavorable win rate reduced property EBITDA by approximately $9 million during the quarter. The result illustrates how fluctuations in gaming outcomes can affect earnings even when operators maintain substantial businesses across the region.
Melco ended the quarter with $2.8 billion in available liquidity, including $1 billion in cash. The company also planned to open REM, its new luxury hotel and entertainment complex, following Golden Week in October.
However, the planned opening comes against a subdued near-term revenue outlook. Jefferies separately forecast that Macau gaming revenue for October could fall by 6% to 10% year over year, below market expectations for flat growth.
That projection adds to concerns about the pace of recovery across the region. For Texas Capital, the immediate question is whether Macau’s revenue performance can stabilize enough to support existing earnings estimates and reduce the need for sustained promotional spending.
